When you or a family member join the military, you receive a simple pamphlet that outlines the VA benefits you'll be eligible for. Actually using those benefits is another, more complicated matter. There are many restrictions and a lot of red tape to navigate beforehand, and without help, it can be overwhelming.
In this guide, we'll review the most common VA benefits that most military personnel are eligible for and common problems that beneficiaries encounter while trying to access them. If you know what to expect and leave yourself plenty of time to deal with logistical challenges, you can save yourself a great deal of stress.
Transition Assistance Program (TAP)
In order to be eligible for any VA benefits after separating from the military, you must complete a mandatory course called the Transition Assistance Program. Depending on your rank and role in the military, you'll be expected to complete the TAP somewhere between one to two years prior to separation.
The TAP consists of several modules, the first of which is mandatory. This module covers topics like finding a job, managing a household budget and how best to leverage your military skills in the civilian world. Altogether, these mandatory courses take about ten hours, and you can complete them whenever you have time. Additional, optional TAP modules are available if you want to do a deeper dive on any of the topics covered in the mandatory portion.
Once you complete the required section of the TAP, you'll be automatically marked as eligible for benefits in the VA system. You should still save a hard copy of your completion certificate, though, in case the automated system doesn't work as intended.
Standard VA Benefits
There are no VA benefits for which every single military servicemember is eligible, but there are a handful of standard benefits available to most personnel who meet a few basic requirements. In order to be eligible for most benefits, you must:
- Serve the entire term of your contract and be discharged honorably (though certain exceptions exist, especially for service-related medical discharges)
- Complete all required pre-separation training
- Have been called to active duty and completed that assignment in full, if you were a Reservist or National Guardsman
There are many different sets of eligibility criteria based on your date of initial enlistment and several other factors. Check your enlistment paperwork or the VA website to find the requirements that apply to you.
Medical Treatment at VA Hospitals
Most veterans are eligible to receive healthcare for life at VA medical facilities, but there are a few important things to know about this benefit.
For routine, non-emergency medical care, you'll need to make an appointment at your nearest VA facility and fill out a substantial amount of paperwork. It can take as long as 6 months to get set up in the VA medical system after you separate, so start the process as soon as possible, even if you don't immediately need medical care. You won't be eligible to receive non-emergency healthcare until you receive a notice confirming that your enrollment is complete.
Although the VA hospital system provides medical care at no direct cost to you, it does face some significant logistical challenges you should be prepared to navigate. Long wait times are normal, as are supply and personnel shortages. If you need to see a specialist, you'll first have to go through the primary care system to get a referral, which could take weeks or months. As long as the condition you need treatment for isn't critical or time-sensitive, the VA system can be a good option.
Emergency medical treatment works a bit differently. If you're sick or injured seriously enough to call 911, you can be treated at a VA emergency room at no direct cost to you. But what if there's no VA emergency room nearby, or what if the VA facility is overcrowded and you need to go somewhere else for prompt treatment? In these cases, you'll need to make some tricky financial decisions (ideally, long before you ever need emergency care).
As long as the VA agrees that your condition warranted emergency treatment, they'll pay the bill at any non-VA emergency room or urgent care facility, but there are a lot of asterisks next to this statement. If the VA decides that you didn't need emergency treatment, you can appeal that decision, but if the appeal is denied, you'll be on the hook for most or all of the bill. Also, the relationship that the VA has with non-VA medical facilities is governed by thousands of pages of laws and regulations, and the rules continue to change daily. This means that, even if you do your best to follow them exactly, an obscure law or policy could make you partly responsible for the cost of your treatment at a non-VA facility.
As you can see, decisions about how, where and when to use your VA medical benefits can be complicated and messy. Sit down with your family and make a personalized plan about what you'll do in various medical emergencies. The more thinking and planning you do in advance, the more value you'll be able to get from your medical benefits.
Check here for more information about VA medical benefits.
VA Home Loans
Of all the standard VA benefits, the home loan is one of the most valuable, and it's easy to use. The VA guarantees (but does not underwrite) home loans for veterans, giving borrowers the lowest possible interest rates and the option to buy a home with no money down. Other benefits include:
- Option to decline mortgage insurance, which may otherwise be required and is unnecessary for some borrowers
- No minimum credit score
- Lifetime reusability, no matter how many homes you buy (one home at a time, and it must be your primary residence—no vacation homes)
However, there's a lot of confusion concerning what it takes to qualify for a VA loan. The VA does not disburse or underwrite loans; it only guarantees the loan if a lender chooses to grant it. This means that a lender must judge you to be a qualified borrower, and lenders can impose their own requirements apart from the VA's requirements. This is why you might need to have, for example, a credit score of at least 680 or a 10% down payment; these are the lender's conditions, not the VA's. You can always shop multiple lenders for the best terms, but most will have similar requirements based largely on credit score, income and debt.
When you're ready to buy a home, look for a lender who specializes in VA home loans; they're substantially different from any other type of loan, and you'll want someone who knows how to navigate the process smoothly. In most cases, you'll just have to visit the VA website, print your certificate of eligibility and provide it to the lender. They'll take it from there.
Here's the VA's web page with more information on home loan benefits.
Service-Connected Disability Compensations
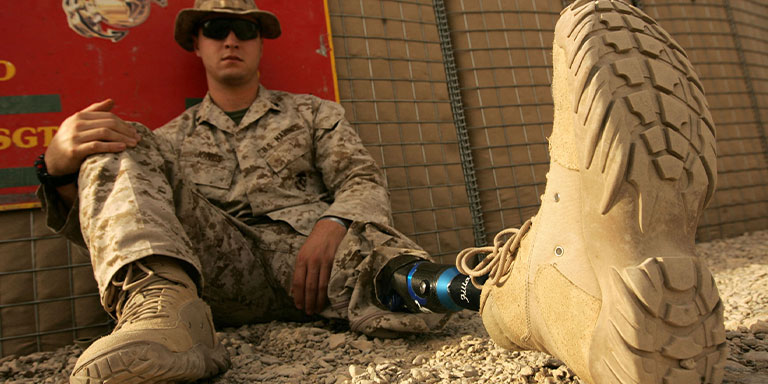
Should you develop a chronic injury or illness related to the performance of your job in the military, you may be entitled to lifetime disability payments. This can be a long and daunting process: you'll have to file a claim with the VA and undergo a series of exams and interviews to determine the cause, severity and prognosis of your condition. These and many other variables are run through a series of complicated formulas to determine the amount you'll be paid. The whole process can take months or even years from start to finish, but once you get through it, payments should be automatic and hassle-free from then on (unless your condition substantially changes, in which case you'll need to be reevaluated).
Here's the relevant VA page with more information about disability benefits.
Preferential Hiring for Veterans
Some (if not most) government jobs offer preferential hiring for veterans. The VA creates and manages a point-based system for scoring federal job applicants, and some states use similar systems. In most cases, eligible veterans receive an automatic boost of five or ten points on a 100-point scale. You don't need to do anything to activate this benefit; the government job system you're using to apply will check with the VA and confirm your veteran status automatically.
GI Bill
Most people know that the GI Bill pays for college tuition and school expenses, but many don't know that there are several different versions of it.
The post-9/11 GI Bill is the most common version offered to servicemembers who first enlisted after September 11, 2001. This version offers the greatest range of benefits but is only available to active duty personnel.
The Forever GI Bill isn't exactly its own “version” of the GI Bill; it's more of an upgrade to the post-9/11 version. Signed into law in 2018, the Forever GI Bill expands the list of schools you can attend, removes the time limit for using your educational benefits, and includes many other extras. Most (but not all) veterans who are eligible for the post-9/11 GI Bill are automatically eligible for the extended benefits.
The Montgomery GI Bill is a less comprehensive benefits package. It's further divided into two forms: one for active duty veterans and one for reservists. In general, the Montgomery GI Bill offers less total financial aid and has more restrictions on how you can use the money.
Regardless of which version of the GI Bill you're eligible for, you'll need to start by making an appointment with the military advisor at the school you want to attend. They'll explain the process of verifying your eligibility and help you get signed up for classes.
The VA maintains a page with the most up-to-date information about the GI Bill.
Life Insurance (SGLI/VGLI)
Servicemember's or Veteran's Group Life Insurance (SGLI/VGLI) is life insurance heavily subsidized by the federal government, meaning you can likely get coverage cheaper than you'll find it anywhere else. The two programs are essentially identical, but SGLI is for active military personnel and VGLI is for veterans and retirees. In most cases, you'll need to have an active SGLI policy at the time of separation in order to be eligible for VGLI. Once you're enrolled with VGLI, you generally need to make premium payments for life to remain eligible. If you stop making payments, you may permanently lose access to VGLI insurance.
For more information on SGLI/VGLI, check the VA's website.
Pension
The VA Veterans Pension Program is not the same as your retirement benefits, which will depend on many factors. The VA Pension Program is designed to help low-income and/or disabled veterans pay their bills. In order to qualify, you must not have been dishonorably discharged and your family income must be below a certain threshold that changes every year. In addition, you must:
- Have served at least one day during wartime, and at least one of the following:
- Be at least 65 years old
- Have a permanent and total disability
- Be a patient in a nursing home for long-term care because of a disability
- Receive Social Security Disability Insurance or Supplemental Security Income
There are a few other restrictions related to your time and length of service. For more details, visit the VA Veteran pension information page.
How to File a Claim
Unfortunately, there isn't one central phone number or website you can use to file a claim with the VA. Like any large organization, the VA has many different departments. To get to the right place, visit the VA homepage and find the department you need. The page you land on should have instructions about how to enroll for benefits or file claims.
No matter what sort of claim you need to file, you'll need to gather some documentation if this is your first time utilizing VA benefits. Make sure to have your:
- Photo ID (a high-resolution digital copy, in color)
- Social Security number or VA file number, if you have one
- Military records jacket (especially your enlistment and discharge papers that list the benefits you're eligible for)
- Income and banking information for yourself and any dependents you want to enroll
- Medical records (if applicable)
Depending on what you're trying to do, you may not need all of this information, or the VA representative may ask for more. Gather any military, financial or medical documents you think might be relevant before you start the process to minimize wasted time and effort.
How to Appeal a VA Decision You Don't Agree With
Sometimes, your VA benefits may be denied. There are many reasons this happens: it could be human error, a computer error or you might be trying to claim a benefit you're not actually eligible for. There is an appeal process that varies slightly by department. In general, you'll be allowed to appeal a denial multiple times, but once the VA sends you a notice saying the decision is final, you're pretty much out of luck.
To maximize your chances of a successful appeal, first understand that the appeal process is generally very slow. You'll be required to submit most documents by mail or fax, and it can take weeks or months for someone to review them. Your best bet is to make the clearest, most convincing argument you can in a single message or document, and to send with it any and all documentation that could conceivably help your case. The more relevant information you include at one time, the less you'll need to go back and forth with the VA with long delays between each update.
Second (and third) opinions can be very helpful as well. For instance, if you're appealing a medical decision, try to get letters from multiple doctors with relevant specialties who are willing to affirm the necessity of your treatment.
Finally, be sure to choose the best type of appeal for your case. As of 2019, the VA now offers three different appeal avenues, and you can choose which one to pursue. If you're unsuccessful with one, you're allowed to try the others.
- A supplemental claim review is for submitting new evidence that wasn't available when you first filed your claim.
- A higher-level review is a request to have a more senior reviewer look at your claim. Note that you can't submit new evidence with this type of request.
- A board appeal involves asking the Board of Veterans' Appeals and a Veterans Law judge to review your claim. Although you can start with this option, it's generally best to leave it for last, after you've exhausted the other two routes.
For more information on how to appeal VA benefit decisions, check this page on the VA website.
The VA offers many benefits to veterans and retirees, but in order to take full advantage of them, you'll need to do a fair amount of research and planning. If you fully understand your benefits and how to access them before you separate from the military, you'll be way ahead of the game, and your post-military life will be much easier.